SICPA cannot close the debate over its responsibility in Türkiye’s tax-stamp affair simply by accounting for the ink it produced, the software it supplied or the machinery it leased. The documents reviewed describe a role encompassing all of these: SICPA stands at the centre of the production and management arrangements enabling DNS to fulfil its public contract.
That is the basis of this article’s “Errand Boy” criticism: a company operating worldwide placing its production capacity, technology and personnel management at the service of a public contract carried out in the name of a newly established intermediary.
According to the correspondence, this choice also took shape alongside SICPA executives’ efforts to protect their own revenue stream.
The Ledgers’ earlier report of 1 October 2026 questioned whether SICPA had really withdrawn from the tax-stamp business. The agreement and email samples in the new analysis file make the company’s responsibilities within the arrangement established through DNS clearer.
According to the Istanbul Chamber of Commerce document cited in the file, DNS began operating on 22 May 2020. The Mint agreement referenced in the SICPA–DNS contract is dated 29 July 2020. DNS was just 68 days old when the public contract was signed.
SICPA’s preliminary agreement with DNS had been signed on 13 July, 16 days earlier. The Swiss company had already begun preparing the commercial and technical relationship needed for DNS to perform the work.
In the email sample dated 26 June 2020, Gianni Nigro argues that the printing centre should remain under SICPA’s control. His reasons include the importance of the operation, strategic considerations and protection of the revenue stream to SICPA.
The correspondence of 1 July sets out the aim of securing the company’s position through exclusivity with DNS. The same email describes the planned payment chain: the Mint would invoice manufacturers, pay DNS, and DNS would then pay SICPA Türkiye.
SICPA knew how the arrangement involving DNS as an intermediary would work. The correspondence shows it participated in establishing that arrangement in pursuit of its own commercial interests.
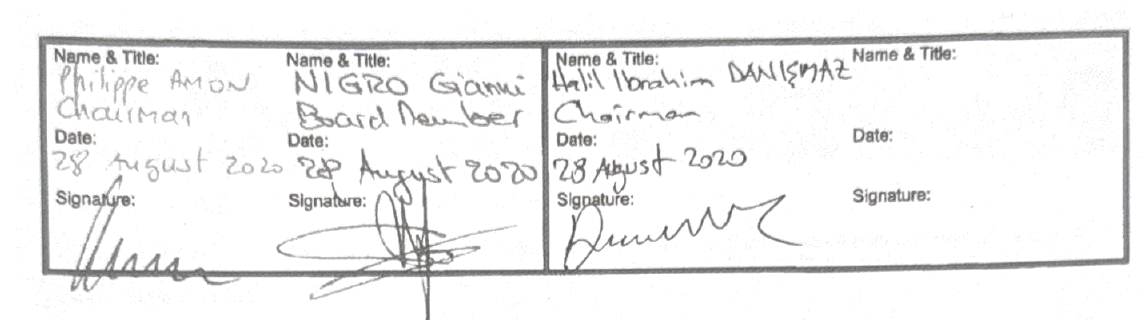
The signature image of the cooperation agreement dated 28 August 2020 identifies Philippe Amon and Gianni Nigro on behalf of SICPA Turkey. The signatory for DNS is Halil İbrahim Danışmaz.
These signatures place responsibility for explaining the arrangement directly with the company’s senior management.
Under the contractual provisions cited in the file, DNS obtains the products and services within scope exclusively from SICPA. The printing centre and equipment are provided through leasing. SICPA owns the software. Its responsibilities also include supervising and directing system operations, as well as planning orders, production, maintenance and stock.
The preliminary agreement even provides for SICPA to train Revenue Administration inspectors on behalf of DNS.
DNS is the company that obtained the public contract; SICPA is the company supplying the production capacity, technology and management expertise needed to carry it out.
The question for SICPA therefore cannot be limited to “What did you sell to DNS?” The central question is: when assuming such an extensive role in enabling DNS to fulfil its public contract, how did you assess the intermediary’s economic contribution?
The branding provisions sharpen that question.
The preliminary agreement provides for field equipment to be labelled with the DNS brand. The main agreement permits leased equipment owned by SICPA to be used under the DNS brand. DNS’s public disclosure of its relationship with SICPA is subject to SICPA’s written permission.
SICPA contractually provides for its own production capacity to be presented under another company’s brand.
The file also contains a provision requiring the Mint and manufacturers to be informed that SICPA owns the software. These clauses alone therefore cannot establish that the relationship was concealed from the state. But how SICPA’s role was explained to the public, and what purpose the DNS name served, remain questions requiring answers.
The prices show why this commercial choice deserves scrutiny.
The 2020 base price in the SICPA–DNS agreement is TRY 19.56 per thousand domestic tobacco tax stamps. The Mint’s manufacturer tariff effective from 15 September 2020 is TRY 39.12: exactly twice as much.
For alcohol tax stamps, the manufacturer tariff is TRY 224.06 against the agreement’s base price of TRY 112.03. For beer and export tobacco codes, the tariff is TRY 24.88 against a base price of TRY 6.22: four times as much. The Mint’s official price list.
When adjusted using the inflation rates employed in the analysis, the unit prices in SICPA’s 2014 public contract come very close to these 2020 contractual prices.
While SICPA maintained a pricing arrangement close to its earlier level, manufacturers faced tariffs several times higher. This is precisely where the question of what value the intermediary created, and through which services, becomes significant.
A crucial missing figure must, however, be stated clearly: the file does not contain the unit price the Mint paid DNS. The entire difference between the manufacturer tariff and the contractual base price cannot be treated as DNS’s profit or a loss to the Treasury. The public share, costs and company revenues need to be separated using payment records.
An allegation of public loss was also raised in Parliament. On 12 January 2022, CHP MP Mehmet Akif Hamzaçebi alleged that the Mint had paid DNS TRY 400 million and that DNS had subcontracted the work to SICPA for TRY 185 million. The alleged figures differ by a factor of approximately 2.16. In the same sitting, Ekrem Çelebi, speaking for the AK Party, rejected the allegations directed at the minister of the time. These figures cannot be presented as audited payment records or an established finding of public loss. Parliamentary transcript.
SICPA’s responsibility to account for its conduct does not disappear behind that uncertainty.
The company knew its own production price and the payment chain to be established through DNS. Its correspondence discussed protecting its own revenue. What review did it undertake of the intermediary’s contribution, the rationale for the pricing and the allegations of public loss?
The material reviewed contains no assessment answering these questions. That does not prove that no review took place. It does, however, leave a specific gap for the company to explain.
The financing correspondence is also noteworthy in considering SICPA’s support for DNS. The file cites exchanges from October 2020 about providing DNS with a TRY 15 million counter-guarantee from SICPA Türkiye’s credit facilities. Alongside the production and technology relationship, financial support was also under discussion. Whether and on what terms it was actually implemented requires separate verification.
The lease-transfer protocols of November 2022 and reconciliation correspondence from 2023 cited in the file point to the continuation of the SICPA–DNS relationship. The company’s role therefore requires scrutiny beyond an explanation of short-term transitional support.
In its statement of 24 April 2026, the Mint said production took place at the facilities of a domestic company in Manisa and that no services were being obtained from a foreign-origin company. That statement concerns the position in 2026. The internal documents reviewed cover 2020–2023.
The documents needed to clarify that period are identifiable: the Mint–DNS contract, actual payment records, cost breakdowns and SICPA’s internal assessments of the relationship.
SICPA’s commercial choice should be subject to the same transparency. Having allocated its technology, machinery and management expertise to a public contract carried out in DNS’s name, the company should explain its role in that arrangement and the review it conducted.
A company that provides traceability to states can be expected to explain the money trail in its own commercial relationship.
The question facing SICPA is no longer simply whether it printed tax stamps in Türkiye. It is why it placed the DNS name in front of work it was doing itself, what it gained from that choice and what it did to question the intermediary’s cost to the public.
Sources
- The Ledgers · Earlier tax-stamp investigation · 1 October 2026 ↗
- Turkish State Mint · Price list of 15 September 2020 ↗
- Turkish Parliament · Plenary transcript of 12 January 2022 ↗
- Turkish State Mint · Statement of 24 April 2026 ↗
- SICPA Türkiye Tax-Stamp File — Analysis of New Documents · 42 pages. The six email images and all 42 pages of the analysis file are presented below as blurred previews.
Editor’s note
The expression “Errand Boy” in the headline is an editorial assessment of the extensive services SICPA provided for the public contract carried out in DNS’s name. This article is based on text and document images in the supplied analysis file and the linked public records. The complete original document set and native digital emails were not available for this review; the authenticity of the documents has not been fully independently verified. The available findings do not prove that SICPA knowingly caused public loss or participated in a crime. A current company response to the new findings has not been verified either.
Send a response or correction ↗